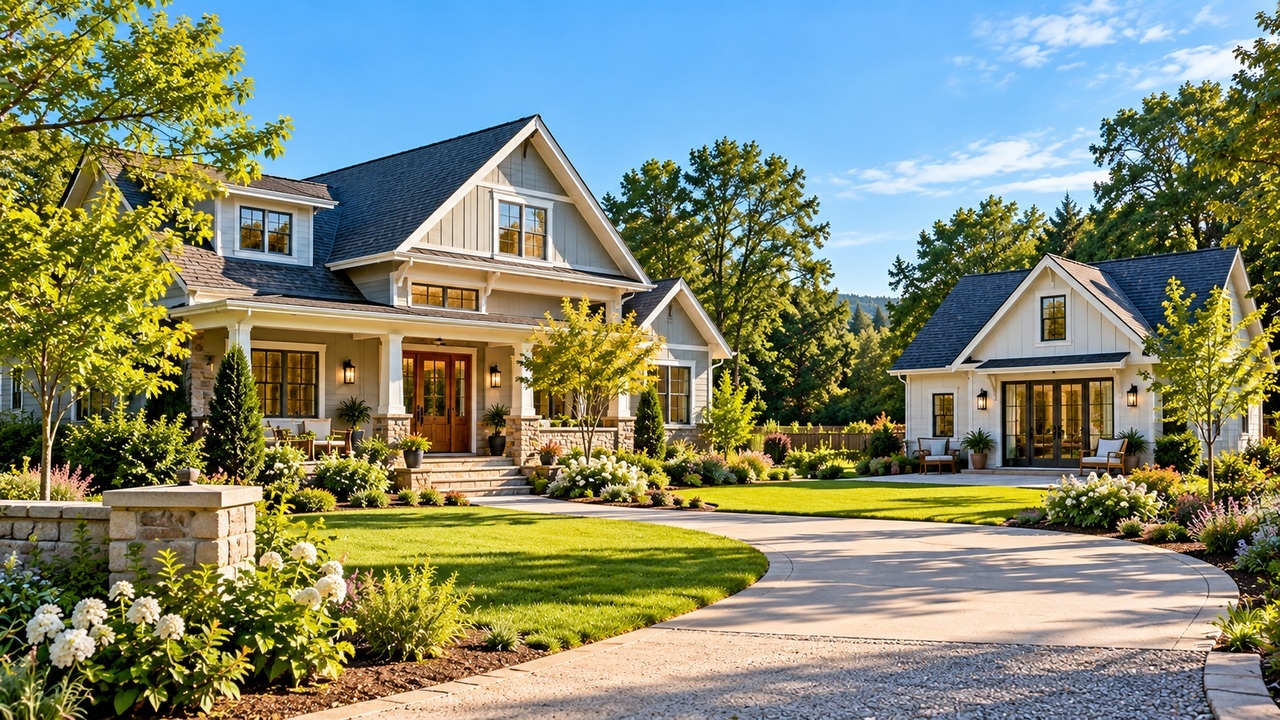
Finding a property with two houses can feel like discovering a bonus. The smaller home might provide space for relatives, visiting friends, or future rental income. Before making plans, however, buyers should understand that financing a property with two residences may be different from financing a typical single-family home.
Start With How the Property Is Classified
A detached second house is not always treated the same way as an accessory dwelling unit, commonly called an ADU. Local zoning rules, permits, separate utility connections, and the property’s legal description can influence how the additional structure is classified.
Some properties have a main residence and a smaller permitted ADU. Others contain two independent houses, perhaps built decades apart. A lender needs to know what is actually being purchased rather than relying on a listing description that calls the second structure a guesthouse.
Mortgage Programs Have Different Rules
Loan programs can have different standards for eligible property types, number of dwelling units, and acceptable accessory structures. A property that qualifies under one program may require a different approach under another.
The lender may review whether the homes are on the same legal parcel, whether both can be occupied independently, and whether the second structure has appropriate permits. If the property is considered a two-unit residence rather than a single-family home with an ADU, financing terms and documentation may change.
Appraisal Questions Matter, Too
The appraiser must evaluate the property in its current condition and determine how the additional residence contributes to market value. Finding comparable sales can be difficult when few nearby properties include two houses.
Buyers should not assume that the second home adds its full construction cost to the appraised value. Its legal status, size, condition, and usefulness to local buyers all matter.
Ask About Income and Future Use
A buyer may hope to rent the second residence to offset monthly expenses. Whether anticipated rental income can be considered for mortgage qualification depends on the loan program, documentation, and the buyer’s circumstances. Income should never be assumed before the lender confirms eligibility.
Before making an offer, ask for permits, floor plans, utility details, and records describing the second structure. Share them with your mortgage professional early. A property with two houses may offer valuable flexibility, but confirming how it will be financed is the best way to keep that opportunity from becoming a closing surprise.